


Stablecoin cards cross more than $10.9 billion says RedotPay
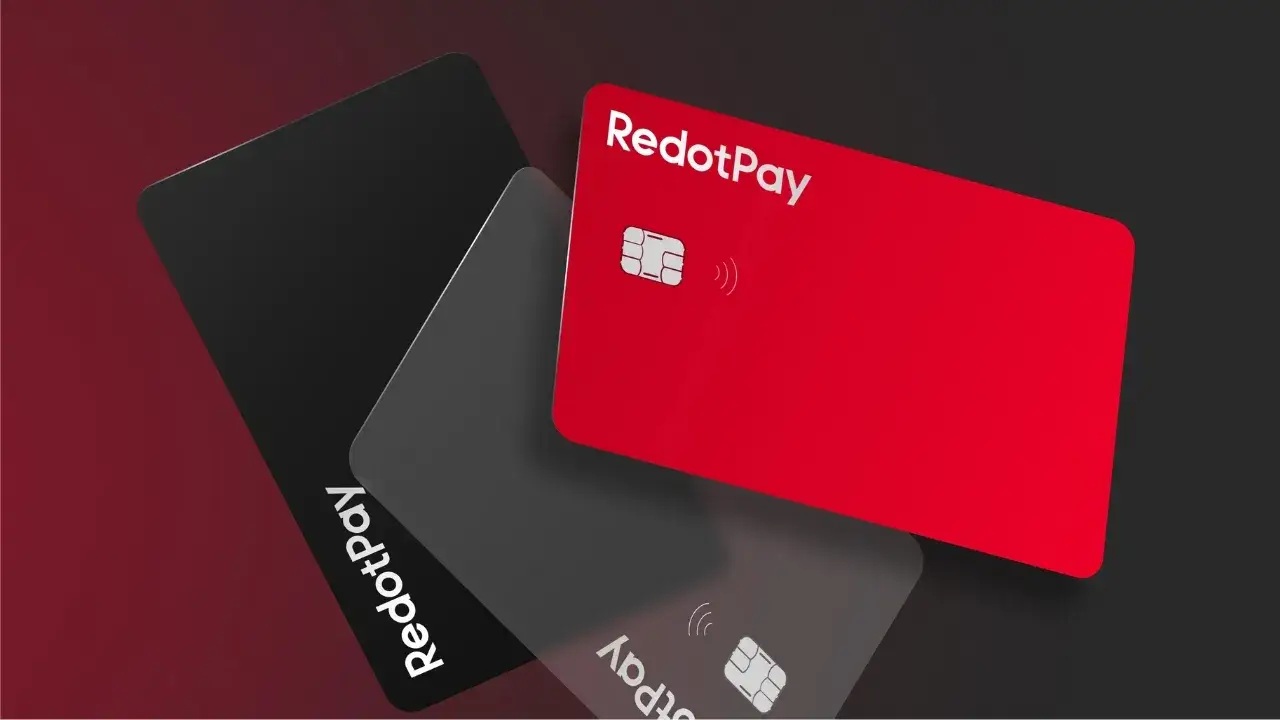
Stablecoin-powered cards are moving from a crypto-native product into a mainstream payments tool, as consumers increasingly use digital dollars for daily spending, subscriptions, travel and cross-border transactions.
According to RedotPay, the industry has now crossed more than $10.9 billion in cumulative stablecoin card spend, with July 2026 marking the sector’s biggest month to date. The company said stablecoin card volume reached about $1.04 billion in July, compared with roughly $339 million in July 2025, citing data from Paymentscan.
The numbers point to a shift in how stablecoin products are being used. Three years ago, RedotPay said the entire industry was processing around $60,000 a month. Today, that volume can be processed in about four minutes.
Stablecoin cards find real-world use
Unlike early crypto products that were mainly associated with trading, stablecoin cards connect digital asset balances to existing card networks, allowing users to spend stablecoins through familiar payment rails while the conversion or settlement happens in the background.
This is why the market’s growth is being followed closely. For users in countries where access to dollar accounts, international cards, mobile wallets or low-cost cross-border payments remains limited, stablecoin cards can provide a practical bridge between digital assets and everyday commerce.
A small business owner can use a stablecoin card to pay for online software. A freelancer can receive digital dollars and spend them without waiting for banking hours. A traveller can keep value in a dollar-linked asset and use a card abroad without depending entirely on local banking infrastructure.
RedotPay says it now serves more than eight million users globally across more than 100 countries, with its card product accepted by more than 130 million merchants worldwide. While the market is still small compared with traditional card payments, the pace of growth suggests that stablecoin-backed consumer payments are becoming a more serious category for fintechs, exchanges, wallets and card issuers.
Why MENA matters
For the MENA region, the rise of stablecoin cards comes at a time when governments, banks and payments companies are already exploring regulated digital money, tokenized deposits and stablecoin settlement.
RedotPay’s own expansion plans also point toward the region. After raising $107 million in Series B funding, the Hong Kong-based fintech said the capital would support product development, compliance, licensing and global expansion, with reports identifying the Middle East and North Africa as one of the markets in focus. The company already positions its stablecoin card and payout services for users in more than 100 countries, a footprint that gives it a natural entry point into MENA’s remittance-heavy and digitally connected markets.
In the GCC, payments infrastructure companies are beginning to test stablecoin settlement with global card networks. NymCard has announced stablecoin settlement capability in the GCC with Visa using Circle’s USDC, while Visa has also expanded stablecoin settlement in the region through its partnership with UAE-regulated Aquanow.
The UAE has also been pushing regulated stablecoin use cases. Network International announced that it would enable regulated AED stablecoin payments using AE Coin in collaboration with Al Maryah Community Bank, giving merchants a way to accept a central bank-licensed dirham stablecoin across physical and digital channels.
This matters because MENA has several conditions that make stablecoin cards relevant: a large remittance market, a young mobile-first population, demand for dollar-linked savings in some markets, and growing government interest in digital payments infrastructure.
Impact on consumers and businesses
For consumers, stablecoin cards could make digital dollars more usable in daily life, especially for people who already hold stablecoins for savings, remittances or online work. Instead of converting back to cash or waiting for bank transfers, users can spend directly through a card interface they already understand.
For merchants, stablecoin payments could eventually reduce settlement friction, support cross-border customers and open new payment options for digital commerce. For fintechs and banks, the opportunity lies in building compliant products that combine stablecoin rails with cards, wallets, local currency conversion and customer protection.
The biggest impact may be in cross-border use cases. MENA is home to major remittance corridors linking the Gulf with South Asia, North Africa and the Levant. If stablecoin cards are paired with regulated on- and off-ramps, they could make it easier for users to receive, hold and spend value across borders while reducing dependence on slow or expensive legacy channels.
Regulation will decide the pace
Still, the region’s growth will depend on regulation, licensing, reserve transparency, anti-money laundering controls and consumer safeguards. The companies that win in MENA are likely to be those that can offer the convenience of stablecoin cards while meeting the compliance standards expected by regulators, banks and payment networks. As stablecoin card spend accelerates globally, MENA is positioned not only as a market for adoption, but also as a testing ground for how regulated digital money can move from infrastructure into everyday payments.
Related Articles

UAE Securities and Commodities Authority and Dubai’s Virtual asset regulator race against the clock to regulate virtual asset entities
April 18, 2023
A UAE based Social impact fund creates watchdog index for crypto and blockchain
April 11, 2024